
Innovation is undoubtedly a major driver of corporate growth. Executives constantly look for ways to innovate to stay ahead of the competition and solve their most pressing problems. Yet, many companies don’t get it right and often confuse innovation with invention.
The short answer: An invention brings ideas or objects together to create a device or process that did not exist before. Innovation is broader: an original and useful idea, whether or not it offers buyers a leap in value. Neither guarantees growth. Blue Ocean Strategy authors Chan Kim and Renée Mauborgne show that new markets come from value innovation, the cornerstone of blue ocean strategy: “the simultaneous pursuit of radically superior value for buyers and lower costs for companies.”
| Invention | Innovation | Value innovation (Blue Ocean Strategy) | |
|---|---|---|---|
| What it is | A device or process that did not exist before | An original and useful idea | The simultaneous pursuit of differentiation and low cost |
| The test | Is it new? | Is it original and useful? | Does it create a leap in value for buyers and the company? |
| Typical outcome | Often limited commercial appeal | May break new ground and win accolades, yet fail to find enough buyers | Unlocks the mass of target buyers and creates a blue ocean of new market space |
| Example | MITS Altair, the first personal computer | Motorola Iridium, the first global phone | Zoom; Apple and IBM in PCs |
Although there is a connection between the two terms, innovation and invention are distinct concepts and shouldn’t be used interchangeably. We’ll take a close look and these terms and related concepts to understand the important difference between innovation vs invention, why you should focus on value innovation instead, and what it all means to your company’s future growth strategy. We’ll explore examples of innovation and invention, as well as examples of value innovation to distinguish the concepts.
The steam engine typically comes to mind when we think of inventions.
What is invention?
Invention is the act of bringing ideas or objects together in a new and unique way to create a device or process that did not exist before. The wheel, paper, steam engine and the internet are typically what come to mind when we think of inventions.
What is innovation?
Innovation is a very broad concept that is based on an original and useful idea regardless of whether that idea is linked to a leap in value that can appeal to the mass of buyers. Corporate graveyards are full of companies that got to market first with innovative offerings not linked to value. Simply creating something original and useful through innovation is not enough to create and capture a new market space, or blue ocean, even if the innovation wins the company accolades.
Innovation vs invention: what’s the difference?
Coming up with new inventions might be personally rewarding but betting your company’s future growth on it is dangerous. The world is filled with new inventions that failed to produce commercial success. Innovation is not invention. So before you run to your research and development department with your new idea, let’s look at some examples to understand the difference between invention and innovation and the results of each.
Invention vs innovation examples
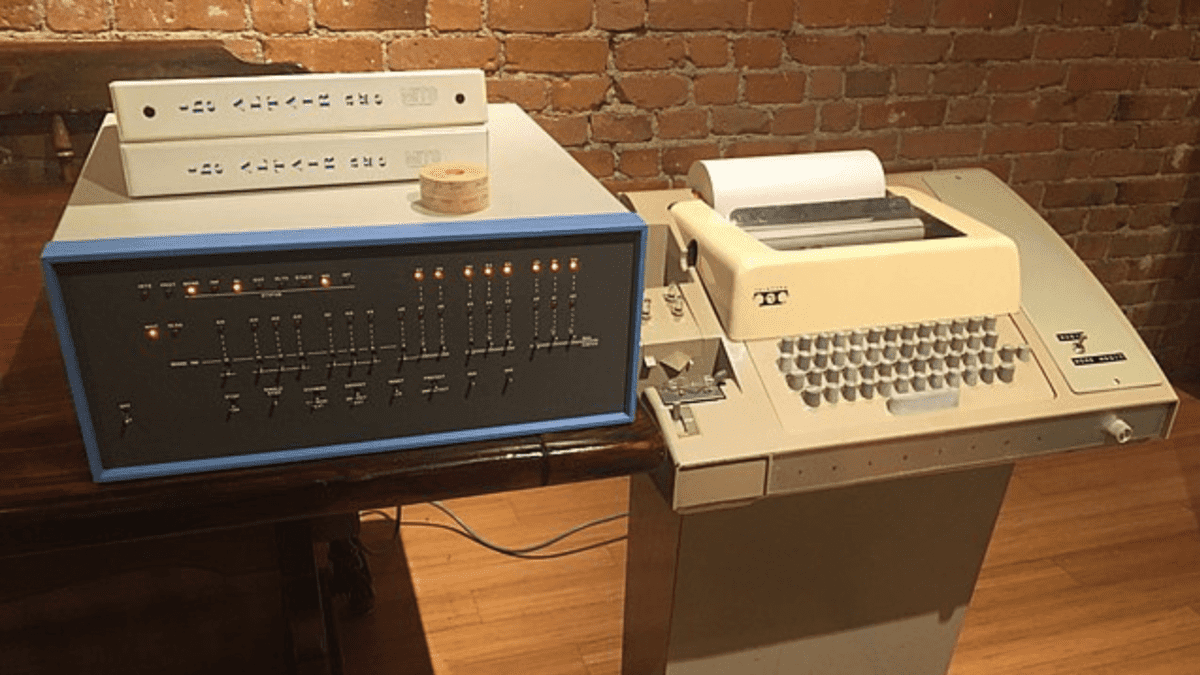
Consider the question of who invented the personal computer. Perhaps you think it was Apple under Steve Jobs or maybe IBM? In fact, it was a small company named MITS, whose personal computer was called the Altair. Popular among computer hobbyists, the Altair had limited commercial appeal, which is why you’ve probably never heard of it.
Or take Motorola’s Iridium. Was it great innovation? Sure. It was the first global phone, but did it offer a breakthrough in value that could attract a mass of buyers? The answer is no. The Iridium was an impressive technological feat that worked in remote places like the Gobi Desert, but it did not work in buildings and cars, the precise places that global executives on the move most needed them to work. It failed to create a leap in value for its target mass of buyers.
To understand why some innovations achieve great success while others are commercial failures, we need to understand the difference between value innovation and technology innovation.
What is value innovation?
Value innovation is a concept developed by professors of strategy and world-renowned management thinkers, Chan Kim and Renée Mauborgne in their global bestsellers Blue Ocean Strategy and Blue Ocean Shift.
Value innovation is the cornerstone of blue ocean strategy and places equal emphasis on value and innovation. It is the simultaneous pursuit of differentiation and low cost, creating a leap in value for both buyers and the company.
Value without innovation tends to focus on value creation on an incremental scale, something that improves value but is not sufficient to make you stand out in the marketplace.
Innovations without value tend to be technology-driven, market-pioneering, or futuristic, often shooting beyond what buyers are ready to accept and pay for, as we saw with the Iridium.
When organizations fail to register the difference between value innovation and innovation per se, they all too often end with an innovation that breaks new ground but does not unlock the mass of target buyers, keeping them by and large stuck in the red ocean of competition. Check out Chan Kim and Renée Mauborgne’s blog on the rising importance of value innovation for creating growth for a more in-depth discussion.
Why technology alone doesn’t create new markets
Technology innovation is the creation of a product or service that focuses on new or improved technology. Often, the technology involved is seen as the differentiating factor and put front and center in the expectation that buyers will find a use for it either now or later.
But when companies mistakenly assume that market creation hinges on breakthrough technologies, their organizations tend to push for products or services that are too “out there,” too complicated, or, like the Segway, lacking a necessary ecosystem.
Read more on the difference between value innovation and technology innovation on the blog: Why technology innovation only counts when linked to buyer value.
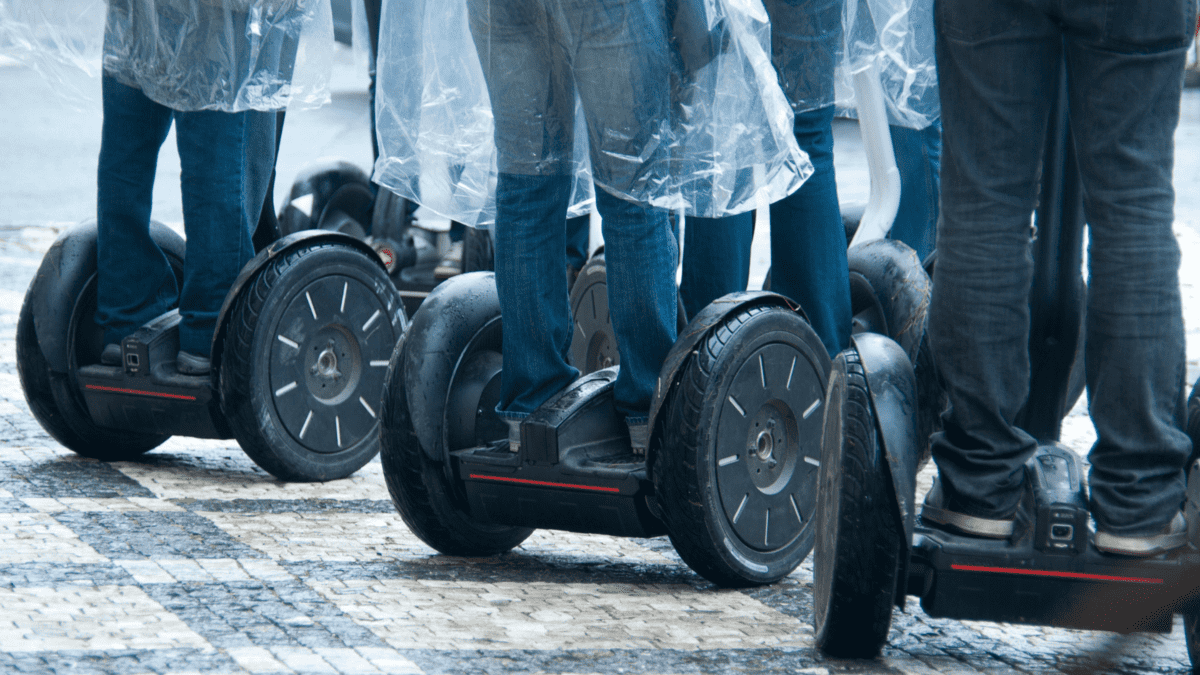
Buyers were not impressed with Segway’s technology innovation.
Examples of innovations that failed
Consider the Segway, the two-wheeled self-balancing vehicle that once promised to revolutionize transport. Technologically innovative, the Segway created a massive media buzz on its launch. Buyers, on the other hand, were less impressed. Most people simply did not want to pay US $4000-$5000 for a product that left them wondering where to park it, how to take it in a car, whether it could be brought on a bus or a train, and where it could be used – on sidewalks or roads.
Technology innovation is widely recognized as the key driver of macroeconomic growth, so you would be forgiven for assuming it is the key to unlocking new markets. Certainly, technology exists to enable value. That is, technology is catalytic to value creation but does not, by itself, guarantee commercial success. It is the value to the buyer that is the most important component of innovation.
Many technology innovators fail to create and capture blue oceans by confusing innovation with value innovation.
Google Glass, Motorola’s Iridium, and Segway all suffered by getting this wrong. Google Glass was considered unattractive, nerdish, and expensive, and raised hugely uncomfortable privacy issues. The Iridium satellite phone was a technological feat that worked in the Gobi Desert but not in buildings or cars, where people needed it most.
Although MITS invented the first personal computer, it was Apple and IBM, among others, that dominated the new mass market for PCs by adapting the technology to produce a leap in buyer value – in essence, converting technology innovation into value innovation.
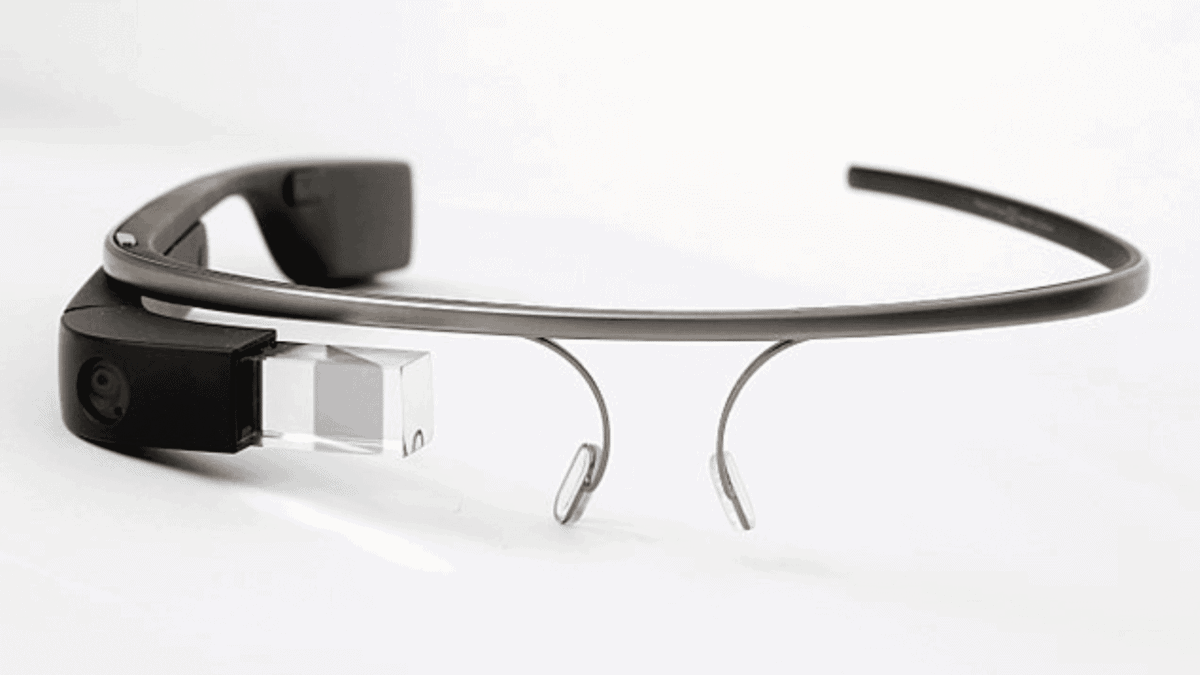
Example of innovation that succeeded
Zoom – an example of value innovation
Zoom is a successful value-innovation business that made high-quality, reliable video conferencing easy. Users love Zoom for the simplicity of setup, use, relatively low cost, and quality of the calls.
Zoom didn’t invent the technology – there were other videoconferencing services long before Zoom came along. Videoconferencing was initially developed in the 1950s, and web-based videoconferencing has existed since the 1990s.
Since then, countless web-based videoconferencing companies have emerged but whereas these services could be difficult to set up or suffer substantially lower call quality, Zoom vastly simplified setting up and joining a video call and made sure the calls were clear and seldom or never dropped.
Zoom made the installation and use of this mature technology far easier, allowing a wider group to unlock and realize the utility without the hassle. A click or two are all that is required to start or join a high-quality online video conference. Zoom is a value innovation. For more examples of value innovation, check out Michael Olenick’s case study: Searching for Value: Value Innovation vs Technology Innovation.
Zoom is an example of value innovation.
How to invent something …people want
So how to invent something that people actually want to buy? You might have a great idea for a new product, an improvement of an existing product, or new solutions to existing problems. But how to ensure your organization can make this a commercial success? First, you need to link value to innovation. Second, run your new idea through a Blue Ocean Idea Index to check whether it is a value innovation or an invention that will not be commercially viable.
Link value to innovation
Value innovation, not technological innovation, is what counts when creating new markets. Starbucks, for example, turned the coffee industry on its head by shifting its focus from commodity coffee sales to the emotional atmosphere in which customers enjoy their coffee – an example of value innovation. No new technology was involved.
Or take Google. It didn’t invent the search engine but nevertheless became hugely successful because it offers buyers a huge leap in value. Its search engine is easy to use, fast, and accurate, making people more productive in finding information than most ever imagined possible. Everyone from first graders to senior citizens uses it.
With its search engine, it was Google’s value innovation rather than technology innovation that created new markets by offering a leap in productivity, simplicity, ease of use, convenience, fun, and environmental friendliness.
However, while Google enjoyed extraordinary success with its search engine, another one of its products, Google Glass, became a commercial failure.
Run your new concept through the Blue Ocean Idea Index
Blue ocean strategy offers a robust way to maximize your upside while minimizing risks. A key framework here is the Blue Ocean Idea Index, which lets you test the commercial viability of your new ideas. It poses four questions:
| Blue Ocean Idea Index | |
|---|---|
| Utility | Is there exceptional utility? Are there compelling reasons to buy your offering? |
| Price | Is your price easily accessible to the mass of your target buyers? |
| Cost | Does your cost structure meet the target cost? |
| Adoption | Have you addressed adoption hurdles up front? |
© Chan Kim & Renée Mauborgne. Blue Ocean Strategy. All rights reserved.
The first two questions tackle the revenue side of your business model. They ensure that you create a leap in net buyer value. The third question deals with the profit side of your business model. And the last question encourages you to think about the externalities that could trip up even the best new idea.
Each of these questions comes with tools and frameworks – so you can get systematic about creating your blue oceans.
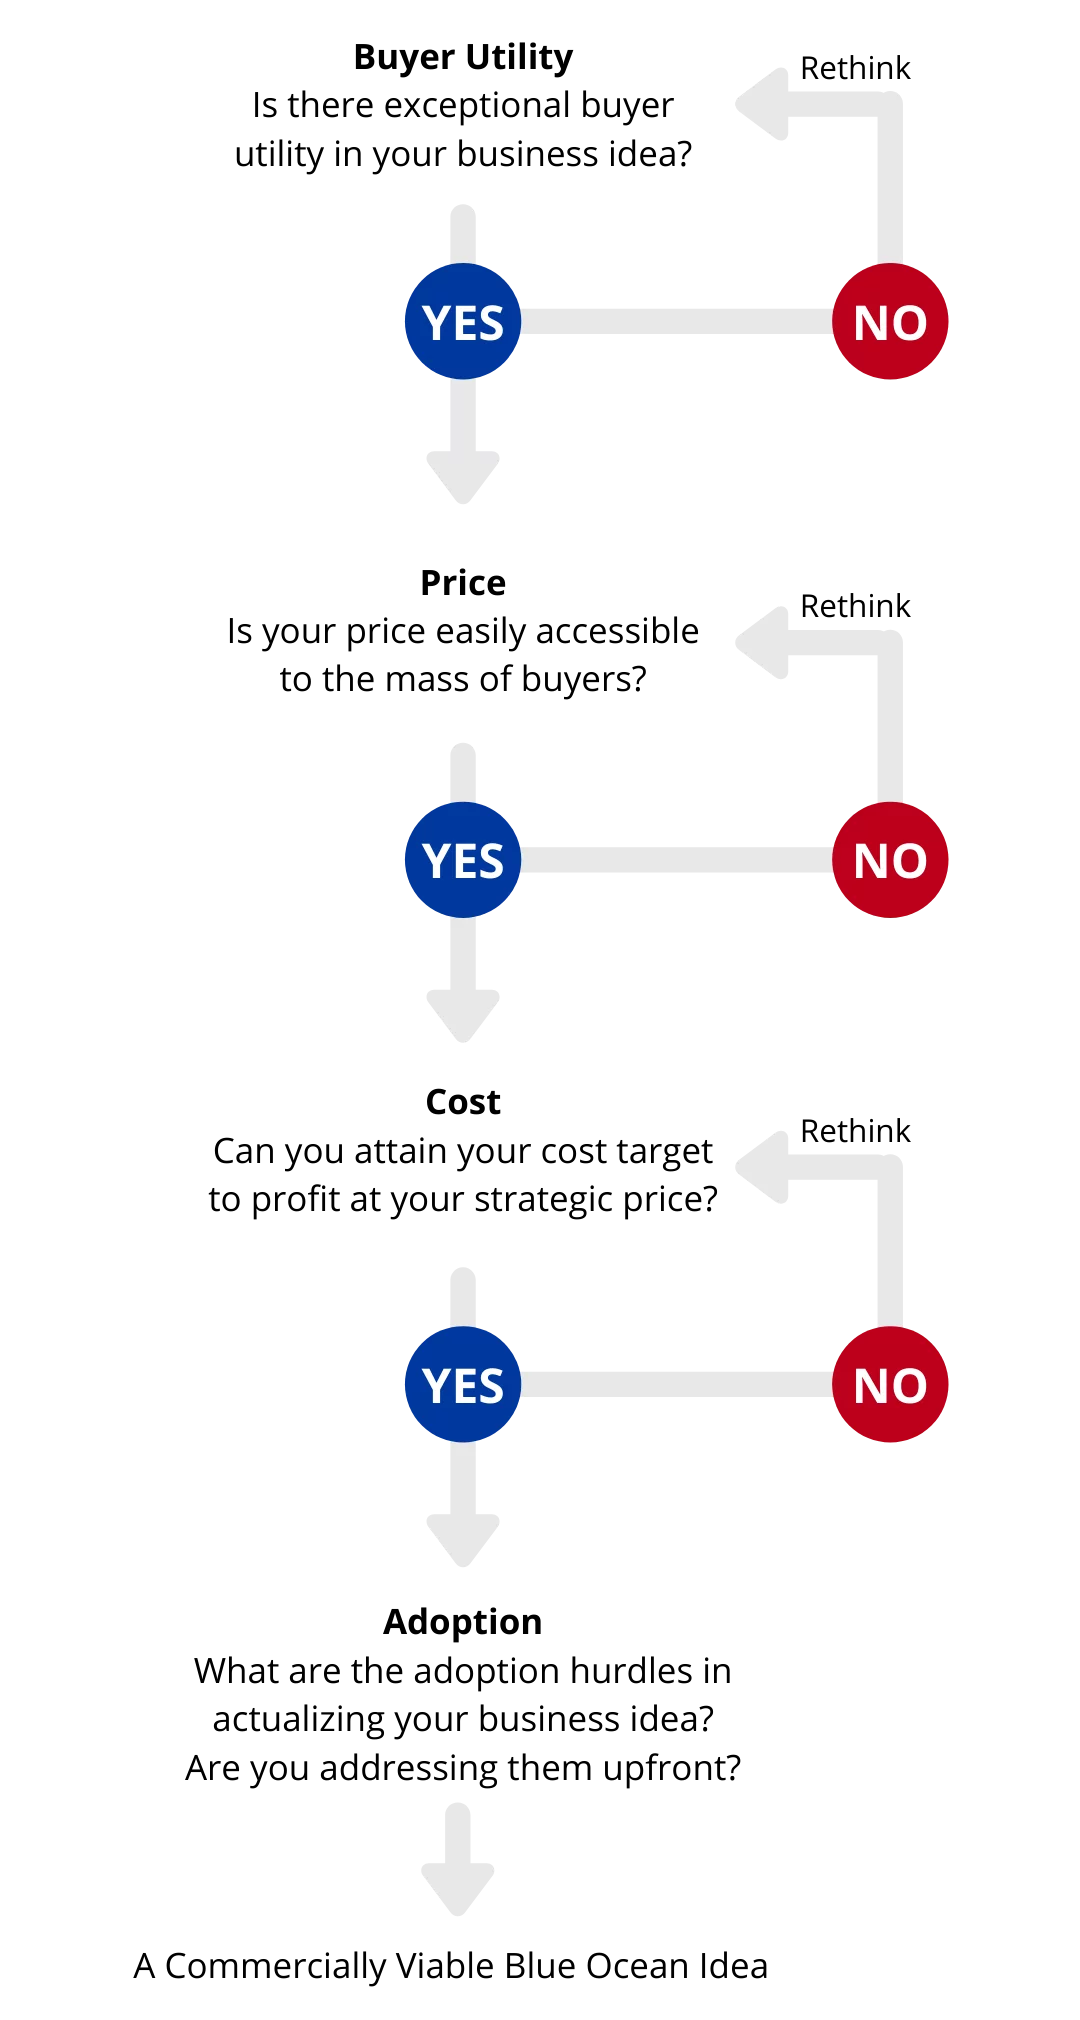
Sequence of creating a blue ocean.
Free worksheet
Test your idea with the Blue Ocean Idea Index
Run your idea through the four questions: buyer utility, strategic price, target cost and adoption hurdles. The worksheet takes you through each step, with space to write your reasoning and a summary table to review the result. Fill it in on screen or print it.
We’ll email you the worksheet.
Innovator vs inventor: which one are you?
So are you an innovator or an inventor? Ask yourself: are you pursuing value innovation or simply trying to invent or develop technology that will make a splash without creating new markets?
If you cannot immediately describe the value of the technology to your buyer in terms the buyer can understand, then you need to reconsider your offering.
Remember, value innovation rejects the value-cost trade-off: more cost does not always equate to more value. That’s why value innovation strategic moves often cost less to produce and are often as profitable or more profitable than technology-focused innovation.
Innovation vs improvement
What’s the difference between innovation and improvement
At this point, it should be noted that innovation is not the same as improvement, which is usually iterative and incremental, coming about through trial and error and getting rid of flaws. Improvement comes after innovation, which involves developing something essentially novel which can then be further improved or optimized.
Simply creating something original and useful through innovation is not enough to create and capture a blue ocean of uncontested market space.
When you fail to register the difference between value innovation and technology innovation or invention, you risk ending up with an innovation that breaks new ground but does not unlock the mass of target buyers.
Remember that while technology innovators may lay extraordinary eggs, they are seldom the ones who ultimately hatch them. The focus of your successful market-creating strategy should not be on how to lay a technology egg per se, but rather on how to hatch the egg for its commercial success.
Frequently asked questions
Is AI an invention or an innovation?
AI is a technology, and a technology on its own creates no market. Whether an AI product becomes a value innovation depends on what it does for buyers. Kim and Mauborgne’s advice is to get the sequence right: start with strategy, identify the leap in value for buyers, and only then use AI as the tool to deliver it. See AI and Strategy.
What is more important, invention or innovation?
For a company’s growth, innovation matters more: many market creators build on technology they did not invent. Innovation alone is not enough either. In Kim and Mauborgne’s words, “Value innovation, not technology innovation, is what opens up commercially compelling new markets.”
Are innovators and inventors the same?
No. The inventor creates something new; the company that links it to buyer value usually wins the market. MITS created the first personal computer and Ampex was first in video recorders. Both, as Kim and Mauborgne put it, “laid the eggs only for other companies to hatch them.”
What are some examples of invention and innovation?
- Inventions: the wheel, paper, the steam engine and the internet.
- An invention with limited commercial appeal: the MITS Altair, the first personal computer.
- Innovations not linked to value: Motorola’s Iridium, the Segway and Google Glass.
- Value innovations: Zoom, Google search and Starbucks, none of which relied on new technology.
Includes excerpts from Chan Kim & Renée Mauborgne’s Blue Ocean Strategy (2015) and Blue Ocean Shift (2017) and the case study “Searching for Value: Value Innovation vs. Technology Innovation”, written by Institute Executive Fellow at the INSEAD Blue Ocean Strategy Institute, Michael Olenick, with Chan Kim & Renée Mauborgne.